Fourteen NSE/BSE-listed companies touch this value chain today. They range from a ₹3.28 lakh crore defence PSU to a company that only became publicly traded in February 2026 via a reverse merger into a dormant telecom shell. Market capitalisation, on its own, tells you almost nothing about how much of a company's business is actually aerospace, or how far up the value ladder of §5 it sits — which is the first thing to sort out before any of the numbers in the individual company reports mean anything.
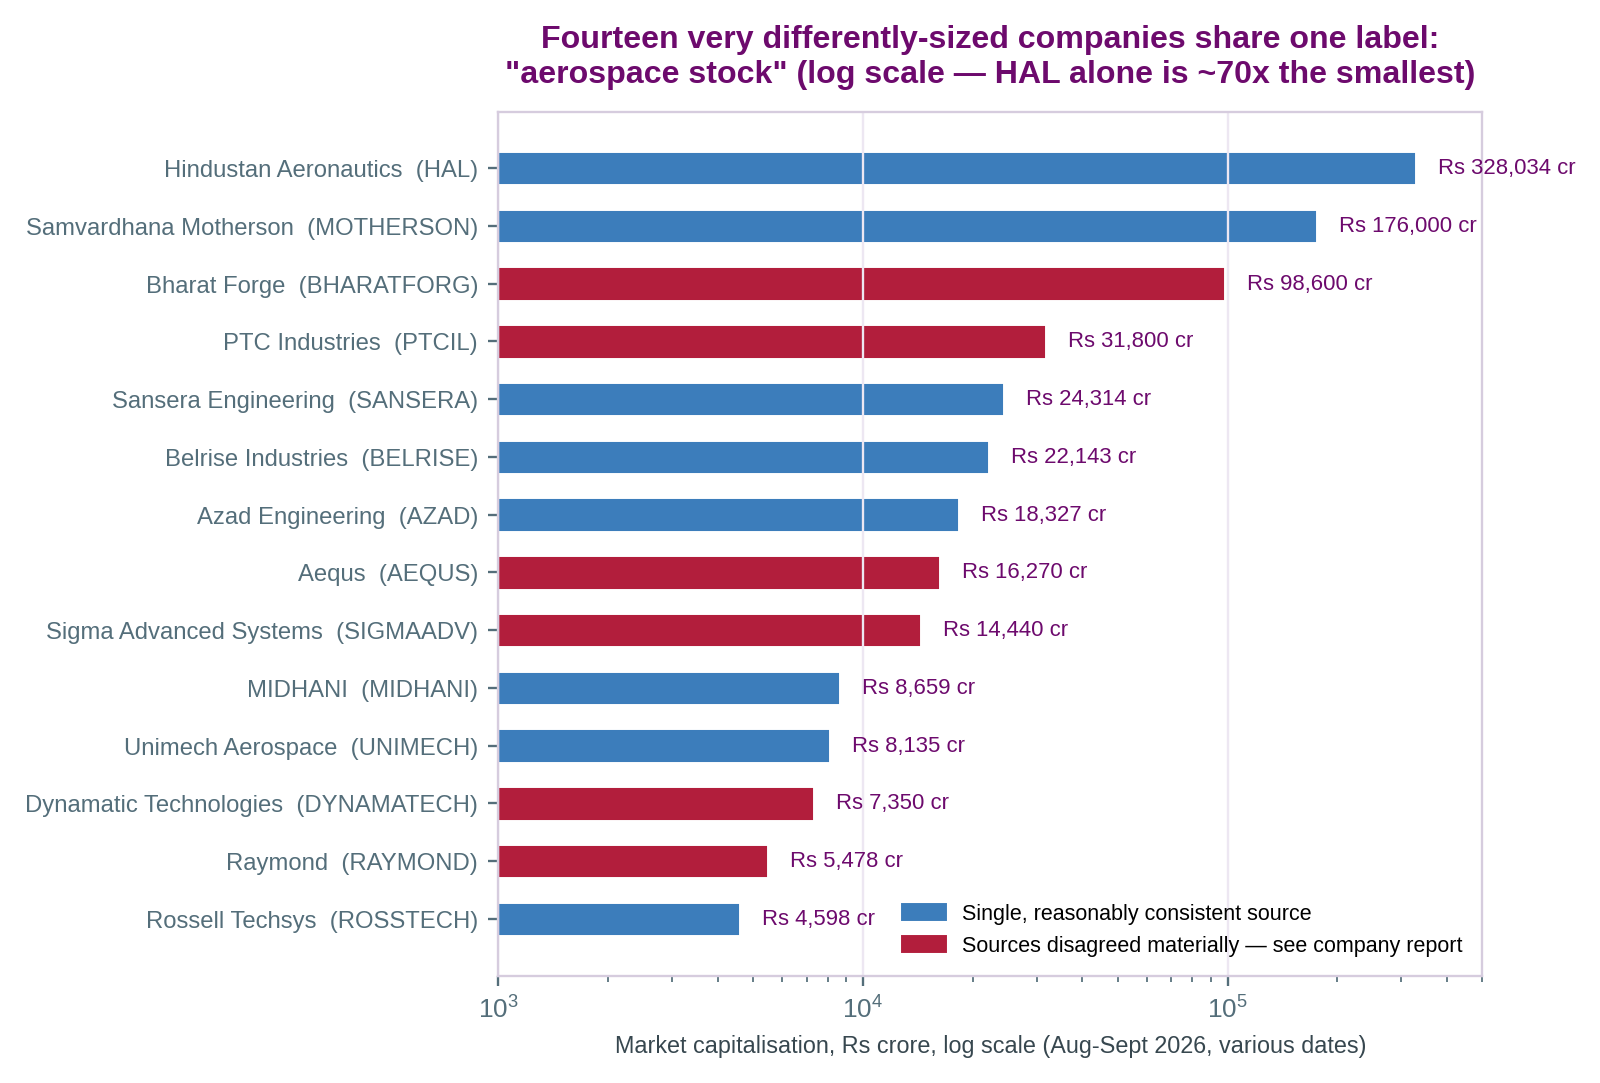
Splitting the fourteen by how central aerospace actually is to the business — based on segment disclosure where a company breaks one out, and on business description where it does not yet — produces a cleaner picture than market cap alone:
| Aerospace is the identity | Aerospace is one segment among several |
|---|---|
| Hindustan Aeronautics — aircraft, helicopters, engines are the whole business | Samvardhana Motherson — aerospace ~1.5% of FY25 group revenue (₹1,749cr of ₹1,12,540cr), though the order backlog has risen $1.2bn→$1.9bn since FY24 |
| MIDHANI — titanium/superalloys, majority aerospace & defence | Bharat Forge — Aerospace & Defence is one of several segments alongside auto components and industrial |
| PTC Industries — titanium/superalloy castings, aerospace-focused Aerolloy subsidiary | Sansera Engineering — Aerospace/Defence/Semiconductor (ADS) is a small, fast-growing segment (₹145.4cr) inside a larger auto-components business |
| Sigma Advanced Systems — aero-engine, avionics & defence electronics across India and UK (Nasmyth, Bromford) | Raymond — aerospace subsidiary JKMGAL is ~17% of FY26 consolidated revenue (₹392cr of ₹2,312cr) inside a smaller post-demerger holding company — a growing weight, not yet a majority |
| Unimech Aerospace — aero-engine/airframe tooling is ~80% of FY26 revenue | Belrise Industries — aerospace exposure is brand-new (Mar 2026 UK Chester Hall acquisition), targeted at ~10% of revenue medium-term, immaterial today |
| Rossell Techsys — pure-play aerospace/defence wiring since its Aug 2024 demerger | |
| Azad Engineering, Dynamatic Technologies, Aequs — aerospace-heavy, but each also carries a non-aerospace segment (energy/industrial, hydraulics, or consumer products respectively) whose exact weight is confirmed in each company's own report |
Source: Dart Consultants, from company segment disclosures gathered for each company's own report (see part 4). Where a segment split is not yet independently confirmed, the company is placed by business description only and flagged for confirmation in its report.
A company where aerospace is 100% of the identity is not automatically the better investment — it is simply the one where the aerospace thesis and the stock price cannot hide from each other. A company where aerospace is 1.5% of revenue, like Motherson, can carry real optionality without the stock being an aerospace bet in any way that matters today. Read every ratio in the individual reports against which bucket, above, the company sits in.
| Company | Ticker | Primary value-chain layer | Listing note |
|---|---|---|---|
| Hindustan Aeronautics | HAL | Complete aircraft, engines, MRO | Long-listed PSU |
| Samvardhana Motherson | MOTHERSON | Wiring (EWIS), structures, hydraulics | Long-listed; aerospace is a newer division (2022-23 acquisitions) |
| Bharat Forge | BHARATFORG | Forgings, engine components, structures | Long-listed; A&D is a reporting segment |
| PTC Industries | PTCIL | Titanium/superalloy castings (materials) | Long-listed; Aerolloy plant inaugurated May 2025 |
| Sansera Engineering | SANSERA | Engine casings (ADS segment) | Long-listed |
| Belrise Industries | BELRISE | Nacelles, aerostructures (via Chester Hall, UK) | Listed IPO; aerospace deal signed Mar 2026 |
| Azad Engineering | AZAD | Engine assemblies, airfoils, actuators | Listed IPO, Dec 2023 |
| Aequs | AEQUS | Aerostructures, forging, machining | Listed IPO, Dec 2025 — very recent |
| Sigma Advanced Systems | SIGMAADV | Engine components, avionics, defence electronics | Listed via NCLT reverse merger into shell "Megasoft," effective Feb 2026 |
| MIDHANI | MIDHANI | Titanium alloys, superalloys, special steels | Long-listed PSU |
| Unimech Aerospace | UNIMECH | Aerospace tooling (jigs, fixtures, engine tools) | Listed IPO, Dec 2024 — ~87% listing-day pop |
| Dynamatic Technologies | DYNAMATECH | Aerostructures (wings, hatch doors), hydraulics | Long-listed |
| Raymond | RAYMOND | Engine components (via JKMGAL subsidiary) | Long-listed; reshaped by 2024-25 Lifestyle/Realty demergers |
| Rossell Techsys | ROSSTECH | Wire harnesses, electrical interconnects | Demerged from Rossell India, listed Aug 2024 |
Raymond's aerospace exposure is real but structurally indirect — the business sits in an unlisted subsidiary, JK Maini Global Aerospace Ltd, formed from the November 2023 acquisition of Maini Precision Products; an investor buys it only by buying Raymond Ltd shares, and Raymond itself has been reshaped by two large demergers (Raymond Lifestyle, 2024; Raymond Realty, 2025) in the same window. Sigma Advanced Systems only exists as a public company because of a reverse merger into a 27-year-old dormant telecom shell (Megasoft Ltd), completed via NCLT order in December 2025 and effective February 2026 — a listing route that at least one independent analysis explicitly recommends treating with more caution than a conventional IPO, pending several quarters of clean post-merger results. Neither point makes either stock uninvestable; both are exactly the kind of structural detail this report exists to surface rather than gloss over. Full 9-page reports for each of the fourteen companies — financials, governance assessment, SWOT, valuation and rating — follow this primer; see each company's own report for the fullest, most current picture.
